


I Asked a Killarney Realtor How Offers Really Work
You’ve found a home in Killarney that looks like a fit. Suddenly, you’re being asked for a price, a deposit amount, and a possession date-a quick shift after months of saving and browsing. Before you sign, make sure you understand what you’re committing to, what you still need to find out, and how much room there really is in your budget.
A note on the title: this is a practical explainer, not a reported interview. Think of it as a guide to the conversation you should have with your Realtor before making an offer in Calgary’s Killarney/Glengarry neighbourhood.
What a Killarney Realtor Means by a Strong Offer
A strong offer combines price, certainty, and timing in a way that appeals to the seller. The highest price may win, but conditions, deposit arrangements, and a possession date that suits the seller’s move also matter. You’re looking for terms you can comfortably honour. Making the transaction easier for the seller shouldn’t come at the expense of protecting yourself.
A seller who has already bought another home, for instance, may put real value on a particular possession date. If it fits your lease and mortgage arrangements, being flexible could strengthen your offer without raising the price. Dropping a financing condition before your lender has reviewed the property is another matter entirely. That puts substantial risk on you.
When looking for a top killarney glengarry real estate agent, ask how they assess competing offers and talk buyers through contractual risk. Find out what the seller’s representative has actually confirmed about timing and competition, rather than relying on assumptions. There may still be gaps: knowing other offers exist doesn’t necessarily mean you know their prices or terms.
Price, Comparable Sales, and Your Budget
The asking price tells you where the seller wants to start; it doesn’t establish market value. Comparable sales-recent sales of reasonably similar properties-help you work out a defensible price range. Active listings are useful for seeing what else you could buy, but there’s a distinction worth remembering: those owners haven’t necessarily found anyone willing to pay their asking prices.
Comparing homes in Killarney takes more than a matching bedroom count. An older detached house, a newer semi-detached infill, and a townhouse can meet different needs and come with different ownership costs. Look at lot dimensions, building age, condition, parking, basement development, and proximity to busier roads such as 17 Avenue SW. The less visible details matter, too. A renovated kitchen won’t tell you whether the roof or sewer line needs attention.
Your Realtor should be able to explain why each comparable is relevant. Perhaps the closest sale had a larger lot or a substantially different level of finish. Ask how those differences affect the suggested price range. There’s judgement involved in these adjustments, not a precise formula that delivers one unquestionably correct price.
From there, separate market value from personal affordability. A mortgage pre-approval may let you borrow more than you’d feel comfortable carrying. Set your offer ceiling around the full monthly cost: mortgage payments, property taxes, insurance, utilities, any applicable condo fees, and maintenance. You’ll also need money set aside for closing and unexpected repairs. Even if the price is fair for the market, it may still be too much for your household.
Which Offer Conditions Protect You-and When They Matter
Conditions give you a set period to work through specific uncertainties before committing to proceed. How much protection they offer depends on the contract’s wording, deadlines, and notice requirements. Have your Realtor walk you through each one in plain language, and bring in your lawyer if you need help interpreting the legal terms.
- Financing: Gives you time to secure the required financing approval for the purchase. A pre-approval isn’t final approval: your lender still needs to approve both you and the particular property.
- Home inspection: Allows you to have the home inspected and decide how to proceed under the condition’s terms. An inspection can flag concerns, though it won’t uncover every concealed defect.
- Condominium document review: Sets aside time, with appropriate professional help, to review the condominium corporation’s finances, reserve fund information, bylaws, meeting records, and other relevant documents.
- Sale of your current home: May matter if you’re relying on the proceeds of that sale to complete your purchase. A seller, however, may prefer an offer that doesn’t depend on another sale.
With an older Killarney property, ask whether its age and visible condition warrant a closer look-for example, a sewer scope. Newer construction or major renovations raise different questions about permits, warranty documentation where applicable, and unfinished work. The point is to investigate the property in front of you, rather than assume every home of a certain age or type has problems.
Appearance won’t tell you the ownership structure: an attached home isn’t necessarily a condominium. Confirm that first. If it’s a condo, don’t read too much into a modest monthly fee. What matters is what that fee covers and whether the corporation has planned adequately for major work that could affect your future costs.
A short condition period can be difficult to manage in practice. Before committing to a tight deadline, check that your lender, inspector, and document reviewer can actually meet it. Competitive terms still need to be workable.
Deposit, Down Payment, and Closing Costs: Know the Difference
Your deposit is money you deliver under the purchase contract. It’s generally held in trust, then credited toward the purchase when it completes. The contract sets out how much you owe, when it’s due, and who receives it. You aren’t paying extra on top of the purchase price, but you do need the money available by the deadline.
The down payment is the share of the purchase price you pay from your own funds rather than through the mortgage, and your deposit normally counts toward it. Check minimum down payment requirements, acceptable funding sources, and the necessary paperwork with your mortgage professional. Money in an investment account may take time to withdraw and transfer, so don’t assume it’s immediately available.
Closing costs need a separate place in the budget. In Alberta, these include legal services, applicable land title registration charges, adjustments for items such as prepaid property taxes, and other transaction expenses. There’s no provincial land transfer tax, but closing still comes with a bill. Leave room for inspection costs, moving expenses, and insurance too, even if you pay them separately and they don’t appear on your lawyer’s closing statement.
It’s also worth asking what happens to your deposit if the purchase doesn’t go ahead. Properly exercising a condition may allow the deposit to be returned under the contract. Failing to complete a firm purchase, on the other hand, can mean losing that money and facing further claims. Don’t assume the deposit is the most you could lose by walking away.
What Happens After the Seller Accepts Your Offer
An accepted conditional offer is already a contract, complete with obligations and deadlines. Next comes delivering the deposit, finalizing financing, arranging inspections, and reviewing any required documents-often in quick succession. Put each deadline in your calendar, and make sure everyone knows who’s handling what.
An inspection concern may give you reason to ask for a repair or price adjustment, though the seller doesn’t have to agree. What you can do next depends on your condition and the contract wording. A lender’s appraisal below the agreed price needs prompt attention, too. Speak with your mortgage professional about the financing gap and whether it affects your ability to go ahead.
Once you’ve satisfied or waived the conditions in accordance with the contract, the purchase generally becomes firm. From there, keep your finances steady until closing. Taking on debt, changing jobs, or making a large unexplained transfer could trigger another lender review. Check before making any significant changes.
Your lawyer takes care of the legal closing work, coordinating funds and registration. Plan your insurance, utilities, and move around the possession arrangements in your contract. You’ll get the keys only after the required closing steps are complete, so don’t count on unloading the moving truck first thing that morning.
Questions to Ask Before You Sign in Killarney
As you consider a top calgary realtor for your purchase, listen to how they explain the risks and your options if something goes wrong. You should feel comfortable asking basic questions, without being made to feel that a moment’s hesitation will cost you the home. Before signing, check that you can answer these questions in your own words:
- Which sold homes support this price, and how do those comparisons fall short?
- What will I spend on ownership each month, and how much cash will I have left in reserve?
- What uncertainties do my conditions cover, and what are my deadlines for acting?
- Which fixtures, appliances, and other items are included in the written agreement?
- What are my options if financing, the inspection, or possession doesn’t go as expected?
You don’t have to master every contract clause to buy a home. You do need clear explanations, realistic numbers, and qualified help when the stakes call for it. Liking the home is one decision; agreeing to the terms of its purchase is another.
Read More...What to Know Before Giving a Statement to an Insurance Adjuster
After an accident, an insurance adjuster may request a recorded statement about what happened and how the injuries affected daily life. The conversation may seem routine, but the answers can influence fault determinations, medical evaluations, and settlement discussions. A prepared claimant can provide accurate information without guessing, exaggerating, or accepting blame. Knowing the purpose of the interview and setting reasonable limits creates a safer starting point for the claim.
Speaking with an insurance adjuster after an accident may seem straightforward, but the information shared can influence how a claim is evaluated. Questions about the collision, injuries, treatment, and recovery can create complications when answers are rushed or uncertain. Preparation can help claimants communicate accurately and protect their interests; you can view website resources for further guidance.
Understand the Adjuster’s Role
An insurance adjuster works for the insurer, not for the injured claimant. The adjuster gathers facts, reviews documents, evaluates coverage, and estimates the insurer’s financial responsibility. That role does not make the adjuster an enemy, but it requires careful communication. Before speaking, ask which insurer the adjuster represents and whether the request concerns a liability claim, a medical payment claim, or another coverage issue. The claimant should also ask whether the statement will be recorded and request a copy afterward.
Prepare Before the Call
A short preparation period can prevent inconsistent or incomplete answers. Review the accident date, location, sequence of events, police report, photographs, witness information, and medical appointments. Keep a timeline nearby, but do not read prepared answers word for word. Employment information also requires preparation. Know the dates missed, reduced duties, lost wages, and employer documentation available. Avoid estimating future losses unless a medical or financial professional has provided a reasonable basis.
The adjuster may ask about the accident, symptoms, prior medical conditions, missed work, treatment, and household responsibilities. Those questions help the insurer compare the reported injuries with medical records and other evidence. A claimant should answer truthfully while avoiding speculation about facts that remain uncertain.
Avoid Accidental Admissions
An adjuster may ask whether the claimant feels responsible for the accident. Do not accept blame simply to sound cooperative. Describe observable facts and let the evidence determine responsibility. Avoid statements such as “I was fine” when symptoms appeared later. Some injuries develop gradually, and an early statement about feeling capable does not describe the full medical course. A better answer explains what was noticed at the scene and what changed afterward.
Do not minimize recovery problems because of embarrassment or pressure. If treatment has been delayed, explain the actual reason, such as transportation problems, scheduling issues, cost concerns, or uncertainty about symptoms. Accuracy provides context without creating an excuse.
Know What Not to Share
A claimant does not need to provide a complete life history during an initial statement. Answer relevant questions about the accident and claimed injuries, but avoid unrelated medical or personal details. Questions about prior injuries require honest answers. Explain whether an older condition was resolved, unchanged, or affected by the new event. Do not hide relevant history, yet do not diagnose the cause of every symptom without medical support.
Never discuss settlement value during a fact-gathering call unless legal counsel has advised that discussion. Do not sign a broad medical authorization without reviewing its scope. Such forms can allow access to records unrelated to the claimed injuries.
Consider Seeking Legal Guidance
A simple property-damage claim may require limited assistance, but serious injuries, disputed fault, permanent impairment, or extensive treatment deserve legal guidance before a recorded statement. An attorney can explain the claim’s coverage, review proposed authorizations, and attend communications with the insurer. Legal advice becomes especially useful when the adjuster requests a statement before medical treatment is complete. Early opinions about recovery, work capacity, or future care can change as doctors gather more information.
Conclusion
A statement to an insurance adjuster should be accurate, focused, and based on records rather than memory alone. Preparation helps a claimant describe symptoms, treatment, work limitations, and accident facts without guessing or accepting unsupported blame. The safest next step is to gather documents, ask whether the call is recorded, and pause before answering questions about fault, prior conditions, or future recovery. For serious claims, legal advice should come before the interview, not after a disputed statement creates complications.
Read More...How Harrison Law Group Helps Clients Navigate Difficult Legal Matters
A serious legal dispute can affect a person’s health, income, family responsibilities, and future plans. Clients need clear information before deciding whether to pursue a claim, accept a settlement, or take a case to court. Legal support begins with reviewing the facts, deadlines, available evidence, and risks that shape each matter. For people injured in North Carolina vehicle accidents, the process also requires close attention to fault and insurance rules. That review sets the direction for every step that follows.
That rule makes early legal analysis essential. Harrison Law Group helps clients organize the facts surrounding a difficult matter, assess their legal options, and identify issues requiring prompt action. A careful review clarifies which documents matter, which parties may bear responsibility, and which deadlines govern the claim.
Preserving Evidence After an Accident
Evidence often determines whether an injury claim can proceed. After a crash, clients should preserve photographs, medical records, police reports, insurance correspondence, witness contact information, and vehicle records. Vehicle data can provide important support. Event data recorders, dashboard camera footage, phone videos, and location records can help establish when and how a collision occurred. Road conditions, lighting, signs, skid marks, and vehicle damage can support or challenge an account of the crash.
A legal team can organize those materials into a clear account of the incident. This work matters in rural areas, where cameras and witnesses may be scarce, as well as on busy urban roads involving several vehicles and insurers.
Handling Insurance Communications
Insurance companies often request statements, medical records, and other information soon after an accident. Clients need to understand what they sign and how their answers could affect the claim. North Carolina drivers should also review uninsured-motorist and underinsured-motorist coverage. The at-fault driver may have limited insurance or no coverage, leaving an injured person to examine protection available under their own policy.
Legal guidance separates necessary cooperation from statements that could create avoidable problems. A lawyer can review policy language, compare damages with available coverage, and respond to disputes involving medical treatment, seat belts, helmets, or the cause of the crash.
How to Build a Well-Documented Claim
A well-supported claim connects the accident to the injury and the injury to measurable losses. Medical records establish treatment, diagnoses, and recovery needs. Employment records document missed work, while bills and receipts show financial costs. Clients should attend scheduled medical appointments and keep records of symptoms, treatment, prescriptions, and daily limitations. Delayed treatment can give an insurer grounds to argue that an injury came from another source, so medical documentation should begin promptly.
The claim also requires a clear account of liability. Witness statements, photographs, traffic records, and expert analysis can address disputed facts. Each item should support a specific point rather than add unrelated material.
Preparing for Settlement or Court
Many injury claims resolve through negotiation, but a settlement should reflect the evidence and the client’s actual losses. An attorney reviews the proposed terms, explains which rights the agreement releases, and identifies expenses the payment should cover. If negotiations fail, the client needs a case prepared for litigation. Preparation includes filing documents on time, identifying witnesses, organizing exhibits, and presenting a consistent account of the accident. Good preparation also helps the client make informed settlement decisions.
Keeping Clients Informed
Difficult legal matters often involve unfamiliar procedures and uncertain timelines. Regular communication gives clients a practical view of what has happened, what needs attention, and which decisions remain. A productive legal relationship includes plain explanations of legal terms, timely notice of deadlines, and a realistic discussion of risks. Clients should know which records to provide, which communications to preserve, and when approval is needed before an important decision.
Conclusion
Clients facing a difficult legal matter often require more than generic advice. They need a fact-based review, careful evidence preservation, insurance analysis, and an actionable plan involving the next legal steps. In a North Carolina accident claim, even a small dispute about fault can affect recovery, so records should be gathered promptly and communications should receive careful review. A person facing injury-related expenses should collect essential documents, avoid unsupported admissions, and arrange a case assessment before important deadlines pass.
Read More...What Factors Can Lead a Car Accident Claim Into Litigation?
Most car accident claims end through insurance negotiations, but some become lawsuits when fault remains disputed or losses exceed an insurer’s valuation. Litigation often follows disagreements about traffic violations, witness accounts, medical records, vehicle damage, or policy coverage. A claim can also move toward court when deadlines approach, evidence disappears, or neither side accepts the other’s calculations. Recognizing these pressure points helps an injured driver preserve evidence and decide when legal action is necessary.
Fault becomes a litigation issue when drivers provide conflicting accounts, police records leave unanswered questions, or physical evidence supports different explanations. An injured person should discuss the claim with a Wesley Chapel car accident lawyer before giving a recorded statement or accepting a settlement. Early legal review can test liability, identify missing evidence, and preserve arguments about damages and insurance coverage.
Conflicting Accounts and Gaps in Evidence
Evidence often determines whether negotiations succeed. Photographs should show vehicle damage, road conditions, traffic signs, lane markings, lighting, and nearby obstructions. Witness names and contact details should be preserved before people leave the scene or forget what they observed.
A police report provides a useful record, but it does not always settle civil liability. Officers often document statements without deciding every issue that affects a lawsuit. Dash camera footage, traffic surveillance footage, event data recorder information, phone records, and repair estimates can provide additional evidence.
Delays create further problems. Surveillance systems overwrite recordings, damaged vehicles undergo repairs, and witnesses become harder to locate. A party that cannot support a claim with reliable evidence faces greater pressure to accept an unfavorable settlement.
Serious Injuries and Disputed Damages
Insurers often challenge claims when injuries appear minor immediately after a crash but worsen later. Medical records link an injury to the collision, document treatment, and indicate whether symptoms persist. Gaps in care give insurers an opportunity to argue that another event caused the condition. Disputes also arise when an injured person has a prior medical condition. Earlier problems do not eliminate a claim, but medical evidence must explain how the collision changed that person’s condition. Doctors’ records, diagnostic testing, treatment plans, and testimony can clarify the difference.
Damages become harder to resolve when recovery takes months or when they affect future employment. Lost wages require employment records, pay statements, and documentation of missed work. A claim involving reduced earning capacity requires evidence about job duties, work restrictions, expected recovery, and future income.
Insurance Coverage and Settlement Limits
Insurance disputes can push a claim into litigation even when fault appears clear. The at-fault driver may carry policy limits that do not cover medical bills, lost income, property damage, and future treatment. Multiple injured people may also seek payment from the same policy. Coverage questions can involve uninsured or underinsured motorist protection, excluded drivers, commercial vehicles, rideshare activity, or conflicting policy terms. Each policy has its own conditions, notice requirements, and definitions. Insurers often request statements, medical authorizations, and other documents before evaluating coverage.
A settlement offer can create conflict when it ignores documented losses or requires a broad release. Signing that release usually ends the claim against the parties covered by its language. Legal review before acceptance can identify unpaid damages and restrictions hidden in settlement paperwork.
Procedural Mistakes and Missed Deadlines
A claim can reach court because a party misses a filing deadline, sends notice too late, or fails to preserve evidence. Statutes of limitations vary by state and claim type, so an injured person should not rely on general assumptions. Government entities often follow separate notice rules. Litigation also becomes necessary when an insurer denies responsibility, refuses to negotiate in good faith, or stops responding. Filing a complaint starts a formal process that permits discovery, document requests, depositions, and expert testimony. Those tools can reveal facts that informal negotiations never produce.
Conclusion
Litigation usually arises from a preventable gap, such as a disputed fault, incomplete evidence, unclear medical losses, or an insurance response that does not align with the claim. The most useful next step is to preserve all records, avoid making casual statements about responsibility, and track treatment and expenses from the first day. A timely legal review can show whether negotiation remains practical or whether filing suit protects the claim before the applicable deadline closes.
Read More...What to Expect From a Premises Liability Claim
A premises liability claim begins after an injury on property controlled by another person or business. The claim focuses on whether a dangerous condition caused the accident and whether the property owner acted reasonably. Slip-and-fall incidents receive the most attention, but unsafe stairs, poor lighting, defective railings, and inadequate security also give rise to claims. Learning what happens after an accident helps an injured person protect evidence, communicate carefully, and make informed decisions during the legal process.
The Initial Investigation and Legal Review
After an accident, the injured person should seek medical care and report the incident to the property owner or manager. A written report creates a record, but it should describe observable facts without guessing about fault.
Photographs of the condition, surrounding area, footwear, clothing, and visible injuries can support the claim. Witness names, contact information, receipts, surveillance details, and medical records also deserve prompt collection. A New York personal injury attorney can assess whether the property owner had received notice of the hazard, failed to correct it, or failed to warn visitors.
Legal review also helps identify deadlines, responsible parties, insurance coverage, and evidence that could disappear quickly after the accident.
Proving Negligence
Most premises liability claims require proof of negligence. The injured person generally must show the following:
- A dangerous condition existed
- The property owner knew or should have known about it
- The condition caused the injury
Actual notice exists when an owner or employee knew about the hazard before the accident. Constructive notice applies when the condition existed long enough that reasonable inspections should have highlighted it.
The property owner may argue that the condition appeared moments earlier or that regular inspections were reasonable. Evidence such as maintenance logs, employee statements, prior complaints, incident reports, and surveillance footage can address that defense.
Comparative Fault
An insurance company or defense lawyer may argue that the injured person contributed to the accident. Common allegations include distracted walking, ignoring warning signs, entering a restricted area, or wearing unsafe footwear.
A finding of comparative fault can reduce financial recovery under applicable state law. It does not automatically defeat a claim, so injured people should avoid public statements, social media posts, and recorded interviews that misstate what happened.
Medical Treatment and Damages
Medical treatment documents both the injury and its effects on daily life. An injured person should follow the treatment plan, attend appointments, and describe symptoms accurately to each provider.
Compensation may include medical expenses, lost income, reduced earning ability, physical pain, and limitations caused by the injury. Severe cases can involve rehabilitation, permanent impairment, or long-term care needs.
The value of a claim depends on documented harm, liability evidence, insurance coverage, and applicable legal rules. A settlement should account for known bills and reasonably expected treatment before the injured person signs a release.
Insurance and Settlement Discussions
Property owners often send claims to an insurer, and the insurance company assigns an adjuster to investigate. The adjuster may request medical records, statements, photographs, employment information, and permission to inspect other records.
An initial settlement proposal does not establish the claim’s full value. The injured person should review the offer against medical expenses, income losses, future care, and the evidence supporting liability.
Written communication should remain factual and limited. A claimant should avoid admitting fault, minimizing symptoms, or accepting payment before understanding whether the amount offered resolves the entire dispute.
Filing a Lawsuit
If negotiations fail, the injured person can file a complaint in the appropriate court before the deadline expires. The complaint identifies the parties, describes the accident, and states the legal basis for compensation.
The defendant then responds, and both sides exchange evidence through discovery. Discovery can include written questions, document requests, depositions, property inspections, and expert testimony about medical conditions or hazardous conditions.
Many cases resolve before trial, but preparation continues as though trial remains possible. A court may dismiss a claim if evidence does not establish notice, causation, or another required element.
Common Delays
Premises liability claims often take time because medical treatment, records collection, insurance review, and evidence disputes require separate steps. Serious injuries require a clearer prognosis before damages can be evaluated.
Delays also occur when several parties control the property, surveillance footage is missing, or the owner disputes how long the hazard existed. Prompt legal action helps preserve relevant records and identify witnesses before memories fade.
Conclusion
A premises liability claim requires more than proof that an accident occurred on someone else’s property. The injured person must connect a dangerous condition to the injury and show why the owner should be responsible.
Medical records, photographs, witness information, maintenance documents, and careful communication shape the case. The next practical step is to report the incident, obtain medical care, preserve evidence, and seek legal advice before signing statements or accepting a settlement.
Read More...What Great Personal Injury Lawyers Do That Others Never Will
After a serious crash, legal representation affects how evidence is preserved and how insurers respond. It also affects a claimant’s chances of receiving fair compensation. Great personal injury lawyers do more than file forms or repeat an accident story. They test every fact, challenge weak assumptions, and prepare each claim for the defenses that can end it early. North Carolina’s fault rules make this discipline especially important. This post explains the habits that separate careful advocacy from routine service.
-
They Investigate Before Blaming
In North Carolina, a claimant who shares even the slightest degree of fault can lose the right to recover damages. This rule makes careful case preparation essential after crashes involving disputed speeds, lane changes, visibility, or road conditions. Personal injury lawyers in North Carolina know that a small inconsistency can affect the entire claim, so they investigate before relying on an insurer’s version.
-
Visiting the Accident Scene
Great lawyers visit the crash scene when conditions allow. They review traffic signals, lane markings, sightlines, shoulder conditions, lighting, and nearby cameras. They also compare the physical evidence with each driver’s account.
-
Investigating Available Evidence
A police report matters, but it does not settle every legal issue. Skilled attorneys examine photographs, vehicle damage, witness accounts, medical records, and available vehicle data before forming a position on fault.
-
They Preserve Evidence Before It Disappears
Evidence often becomes harder to find as time passes. Traffic footage may be overwritten, and damaged vehicles are repaired. Witnesses may forget details, and weather changes the condition of a roadway.
-
Sending Preservation Letters
Careful lawyers send preservation requests when another person, business, or insurer controls relevant material. They seek event data recorder information, dash-camera footage, phone records, maintenance documents, and photographs taken shortly after the collision.
-
Establishing the Medical Link
They also organize medical documentation early. Treatment notes connect the injury to the crash, record symptom changes, and address arguments about prior conditions or delayed care.
-
They Prepare for Contributory Negligence Arguments
A weak lawyer waits for the defense to raise contributory negligence. A great lawyer looks for that argument before the insurance company does.
-
Testing Against Proof
The review includes phone use, speed, following distance, seat-belt use, helmet use, vehicle maintenance, and decisions made immediately before impact. The lawyer then tests whether the available evidence supports each allegation.
This process requires honest advice. If a fact creates risk, the claimant needs to know before making statements, signing releases, or accepting an early settlement. Clear advice prevents avoidable damage to the case.
-
They Treat Insurance As Its Own Investigation
Liability coverage does not answer every payment question. The at-fault driver could have limited coverage, no coverage, or several policies that require separate review.
-
Analyzing Insurance Provisions
A careful attorney identifies the applicable policies and checks uninsured motorist and underinsured motorist coverage. The review also includes household policies, commercial vehicles, rideshare activity, and other facts that affect available benefits.
-
Communicating With Insurers
Insurance communications require discipline. Lawyers help claimants avoid recorded statements that speculate about fault or minimize symptoms. They also compare settlement proposals with documented medical expenses, lost income, property damage, and future treatment needs.
-
They Build a Clear Damages Record
A claim becomes harder to evaluate when its damages remain vague. Great lawyers create a record that connects each loss to a documented event.
-
Gathering Evidence to Prove Losses
They collect bills, wage records, employment information, treatment plans, prescription records, and evidence of daily limitations. The file should explain what changed after the injury, not simply list expenses.
This work also helps distinguish temporary losses from lasting effects. A claimant who cannot work, drive, sleep, lift, or care for family members needs those limitations recorded with dates and supporting records.
-
They Know When Preparation Matters More Than Pressure
Aggressive language does not replace proof. Insurance adjusters respond to organized evidence, clear liability arguments, and a credible calculation of damages.
-
Preparing for Trial
Great lawyers prepare every case as though trial remains possible. This kind of preparation improves settlement discussions because the defense sees the cost of ignoring documented facts.
They also explain decisions in plain language. Clients need to understand deadlines, risks, settlement terms, litigation steps, and the consequences of accepting an offer. A lawyer who communicates clearly gives the claimant adequate control over decisions.
Conclusion
The best personal injury lawyers separate themselves through preparation that begins before negotiations. They preserve evidence, test fault arguments, review every relevant policy, document daily losses, and explain legal choices without empty promises.
After a North Carolina crash, the practical next step is to save photographs, reports, medical records, and insurer messages before contacting counsel. Early organization gives a lawyer usable facts and reduces the chance of a preventable mistake weakening the claim.
Read More...Serhiy Tokarev on AI in Business: Why a Strong Model No Longer Guarantees Results
Serhiy Tokarev Explains Why AI Agents Will Not Save Business Without Process Restructuring
Autonomous AI agents are already conducting audits, negotiating deals, and managing operations. Because of this, it may seem that the corporate world has entered a new era. And this is not just short-term hype: artificial intelligence (AI) is genuinely changing the rules of doing business.
A gap is already visible between companies that are gradually integrating AI into their processes and those that still see it as an off-the-shelf solution. Serhiy Tokarev, an investor and founder of the Tokarev Foundation, explained why AI is becoming essential for business and how it should be implemented to deliver real results.
AI Should Understand Information but Not Always Act Independently
When analysing a startup, AI can become the first analyst. At Roosh, an internal assistant built on Claude ranks a long list by team excellence and market opportunity, returning a short rationale for each company. Analysts begin deeper research with the top 10 instead of checking 100 startups one by one; productivity in initial screening has increased roughly tenfold.
AI takes over the collection of basic facts and saves a significant amount of time. At the same time, Serhiy Tokarev does not rely on the model to decide where to invest. In his view, the final decision, signature, and responsibility must remain with a human.
“I doubt that human oversight of AI is only a temporary stage that will become unnecessary once this technology becomes more accurate and intelligent. According to Deloitte, 47% of corporate users have made decisions based on incorrect model outputs, while 77% of business leaders are concerned about risks associated with generative artificial intelligence. That is why neither full control nor responsibility can be handed over to an algorithm,”notes the founder of the Tokarev Foundation.
The transition of a model from reading information and preparing recommendations to taking independent action must happen only within clearly defined boundaries. Human oversight does not hinder AI. On the contrary, it is what makes the technology suitable for business.
Artificial intelligence is only one component of the entire process. Roosh’s NDA agent, for example, follows a handbook of acceptable terms, proposed changes and issues to escalate. It prepares an initial review and redline that a lawyer checks and refines, reducing processing time from about 1.5 hours to 15–20 minutes. The first deployment also showed why review matters: the agent sometimes rewrote a provision whose different wording was already acceptable. Adding more examples of valid language helped correct this.
Processes Win, Not Models
Serhiy Tokarev is convinced that access to a frontier AI model should not be considered a long-term competitive advantage. Real value comes from deep integration, evaluation systems, and proprietary industry data. Roosh’s unified LP platform built with Claude Code illustrates this: it brings fund materials and updates from more than 60 portfolio companies into one current context, reducing the time spent assembling and reconciling versions for each prospective LP conversation.
“In our portfolio companies, models do not replace teams of specialists — they help them and expand their capabilities. Some AI agents review and analyse information flows, while others synthesise research in fintech, medical technologies, and game development. Their value comes from how they work together,” says the investor.
The question is not whether AI will be able to replace people. The real question is where exactly the model is already creating measurable business value, and where the market is still selling the future instead of the present.
Read More...Blockchain Technology and the Future of Global Supply Chain Management
Global supply chains link businesses across different countries and continents. They encompass a series of activities from manufacturing, sourcing, and production through to distribution and delivery. Every stage needs trusted information about the product and its movement. Blockchain is considered a digital infrastructure that can provide a data recording system and boost information sharing along the supply chain. The technology can also assist enterprises to boost traceability and visibility between the activities. This growing use of blockchain across supply chain processes is also shaping the development of the blockchain in supply chain management market as businesses explore applications beyond basic transaction recording.
From Linear Records to Shared Digital Ledgers
Supply chain information is commonly maintained in separate enterprise systems operated by individual organizations. Such a structure could produce reconciliation work, since the partners sometimes may have different transaction histories, shipment details or product records. Blockchain brings forth a shared ledger that authorized participants can access and update. The ledger offers a common transaction history without one of the organizations needing to be the only authoritative source.
Why Blockchain Is Gaining Attention in Supply Chains
Blockchain is attracting interest as supply chains continue to become more complex and businesses need trusted transparency across sourcing, manufacturing, transportation and delivery. As an enabler of tamper-proof transaction history, improved validation between autonomous parties and paperwork minimisation, it is becoming increasingly significant for sectors dealing with significant information on products and trade.
- Improved Product Traceability: Blockchain can record a series of events connected to a given product from its initial sourcing, processing, transportation and delivery. When combined with common identifiers and processes to capture key pieces of data, this can enable participants to determine its source and track it through the value chain.
- Stronger Transaction Verification: Records written to a blockchain are designed to be difficult to alter without detection, strengthening confidence in shared transaction histories. This can be useful where several organizations need to verify information but do not control one another’s internal systems.
- Reduced Documentation Friction: International trade involves invoices, shipping information, certificates, customs records and other documents that move between multiple parties. UN Trade and Development has highlighted blockchain’s potential to improve information sharing, streamline trade processes and reduce administrative burdens when supported by suitable policy and technical infrastructure.
Supply Chain Traceability Becomes More Data-Driven
Traceability is moving beyond knowing a supplier or destination and increasingly concerns events throughout a product’s lifecycle. For example, the GS1 standard specifies important tracking events like the receiving, packing, shipping and transport. Blockchain can work as a common record of these events, but only if the data inserted into it is truthful. A blockchain can maintain evidence, but cannot determine if the source input was accurate.
- Integration with Identification Technologies: Barcodes, RFID, digital product identifiers and event-sharing standards can connect physical goods with digital records. GS1’s traceability framework emphasizes standardized identification, data capture and information sharing, creating a foundation for blockchain-enabled supply chain applications.
- Improved Recall Management: When organizations can trace batches, components and distribution paths efficiently, they can identify affected products during quality or safety incidents. This can support targeted recalls and reduce unnecessary disruption across unaffected inventory.
Blockchain Applications Across Major Industries
Food and agriculture are some of the most significant applications of blockchain-based traceability due to the ability of products to move through farms, processors, distributors, retailers, and other intermediate organizations before reaching end consumers. Blockchain-enabled systems can track source, processing, and transport information that can be accessed on a permissioned basis. IBM defines this type of blockchain-based food traceability system as a way “for supply chain partners to collaborate and share permissioned information securely”. Pharmaceutical supply chains also demand accurate records as drugs navigate intricate distribution channels in which authenticity, handling, and custody are important considerations.
It may be possible that blockchain technology would enable manufacturers, distributors, logistics providers and healthcare providers to be linked through shared transaction histories, although regulatory requirements, privacy of the data and integration of computer systems issues must be overcome. For example, manufacturing firms can record movement of components and raw materials between suppliers, production facilities and customers. For high-value products, shared source records can also be used to verify origin, maintenance history and ownership changes.
The Growing Role of Smart Contracts
Smart contracts (software contractual rules) are allowed to automate execution of certain actions based on the occurrence of predetermined conditions. For supply chains, they can initiate subsequent steps in the workflow in response to events as well as other contractual (or other) conditions. Their usefulness is contingent upon event accuracy, contractual clarity, and enforceability of the digital transaction. Smart contracts therefore complement supply chain processes rather than eliminating human oversight.
Blockchain Security and Data Governance
Blockchain’s security characteristics are attracting attention, but security is broader than the ledger itself. Organizations must protect user credentials, digital identities, connected devices, application interfaces and data entering the network. Poorly protected access points can undermine an otherwise well-designed blockchain environment.
- Permissioned Network Adoption: Several enterprise SC applications are adopting permissioned blockchain architecture where participating organizations can get specific rights of access. This can best fit the requirement of balanced ownership transparency and confidentiality, in particular in cases where commercial information needs to be kept away from all network participants.
- Growing Blockchain Security Requirements: With more and larger deployments, organizations will have bigger needs for identity, privacy/encryption, access control, monitoring, and governance. These needs will connect supply chain blockchain deployments to the larger blockchain security market, where the protection of digital assets and transactions and the safeguarding of distributed apps (dApps) is a key technology theme.
Interoperability Determines Scalability
Supply chains rarely operate on one technology platform. Manufacturers may use enterprise resource planning systems, logistics providers may operate transportation platforms, ports may use specialized systems, and customs authorities may maintain government databases. In such a system, blockchain layers would require common data structures and interactions so information could be transferred across legacy systems.
Built on standardized identification, capture, and sharing, GS1 promotes interoperability, enabling companies to interlink different technologies without requiring all to implement the same architecture. Sensors connected to the Internet could provide data like temperature, humidity, shock and location during shipping. If confirmed, these sensor events could be reflected throughout a distributed record that provides continuous visibility into product conditions, for example in food or pharmaceuticals.
Challenges Limiting Widespread Adoption
The blockchain doesn’t come up with the answers for everything supply chain related right away. It can bring with it costs of technology integration, disagreements on governance, quality issues with data, lapses in regulation and cooperation between competitors. There are even challenges for the smaller suppliers when entering the blockchain, needing the investment in new software, connectivity, or skills. The World Economic Forum has emphasized, ‘Implementing blockchain-enabled processes takes clear systems governing issues of interoperability, data integrity, inclusivity, and responsible innovation and application’.
The various transactions in the global supply chain create large amounts of data, and not all of these transactions need to be recorded directly on the blockchain. Companies may rely on a hybrid system of blockchain plus traditional databases, cloud infrastructure and other data systems, and choose which records require consensus.
The Future of Blockchain in Global Supply Chains
The future of blockchain in supply chains is going to be more integrated with existing digital infrastructure. New tools like artificial intelligence, Internet of Things (IoT), digital identities, cloud platforms, and uniform traceability data contribute to the extension of distributed ledgers in the form of more information and more automated processes. The UN Conference on Trade and Development has already recognized the ability of the blockchain technology to bring efficiency and security to trade processes, together with the need to offer policy and technical support. These requirements are also connecting supply chain blockchain deployments with the wider blockchain security market, particularly as organizations focus on protecting digital identities, transactions, applications and distributed networks.
With increased adoption, companies will find the need to deploy the blockchain technology for collaborative scenarios. The future shape of the blockchain in supply chain management market will be formed by implementation requirements rather than adoption, for instance, traceability, source documentation, compliance, or transaction verification. From the perspective of Pristine Market Insights, the development of blockchain in supply chains will increasingly depend on how effectively businesses integrate distributed ledgers with existing digital infrastructure and operational processes. The focus is expected to move from blockchain adoption alone toward practical applications such as traceability, compliance, documentation and transaction verification.
Author Bio:
Teja Kurane is a Research Analyst specializing in emerging technologies, supply chain management, industrial automation, and information and communications technology. Her research examines blockchain adoption, digital transformation, technology integration, and evolving industry practices, providing insights into how innovative solutions are reshaping interconnected global supply chains and business operations.
Read More...The Rise of Premium Hospitality: Redefining High-End VIP Tourism in Central Vietnam
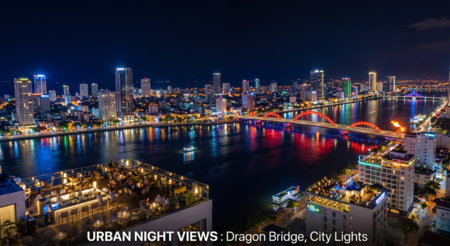
As global travel demands shift toward hyper-personalized and exclusive experiences, the premium hospitality sector in Central Vietnam has adapted by offering fully customized executive itineraries. Modern high-net-worth travelers and corporate groups no longer look for standard tour packages; instead, they demand seamless logistics, absolute privacy, and curated evening entertainment. Driven by this luxury boom, specialized all-inclusive VIP itineraries have become the preferred choice for visitors seeking a stress-free vacation in the coastal city of Da Nang.
An exceptional executive itinerary balances high-end daytime relaxation with vibrant night commerce. A well-structured Da Nang luxury tour package addresses common travel frictions by arranging dedicated private transportation with personal drivers and reserving premium accommodations such as secured private pool villas or luxury beachfront suites that guarantee 100% privacy. Furthermore, these high-end arrangements effortlessly bridge the gap between daytime leisure—such as world-class golf sessions and high-end healing spa treatments—and exclusive night entertainment, including premium private lounge bookings and top-tier hospitality management.
By operating under transparent, pre-arranged premium structures, these comprehensive VIP services eliminate the hidden costs and communication boundaries often associated with independent booking. For the modern lifestyle traveler who values time, comfort, and premium security, investing in a structured local concierge service ensures that every moment of the journey is meticulously handled by local professionals, setting a new standard for luxury travel in Southeast Asia.
Read More...Hot Water Cylinder Leaking: Common Causes and What to Do
The emergence of puddles near the heating equipment can be quite frightening. Nevertheless, in order not to draw premature conclusions about the possible cause of this problem, it would be reasonable to learn the possible origins of the issue first. There can be numerous reasons for the faulty hot water cylinder behaviour.
Why Is a Hot Water Cylinder Leaking?
-
Damaged or Deteriorated Components
Valves, seals, connections, and couplings may wear out over time. In cases where water is found at any of these points, the leakage could actually be caused by the replaceable part and not the cylinder. hot water cylinder leaking from the valve is one such problem that is quite frequent.
-
Corrosion Inside the Cylinder
An old cylinder may experience corrosion in its interior part. Once the cylinder wall gets weakened due to corrosion, it can create a big problem and may need replacement instead of just getting repaired. Periodic inspection will give you an idea about the signs of degradation of your cylinder, which will enable you to prepare for maintenance in advance.
What Should You Do When a Cylinder Leaks?
First, find out where the leaking water originates. If there is water dripping on the floor, put something to catch the dripping. Do not place any electrical equipment around water.
If the leak is significant or keeps getting worse, then you should get professionals to look at it. How to fix a leaking hot water cylinder depends on what is causing the leak. It can be due to a fitting, valve, pipework, or the hot water cylinder itself.
Signs the Problem Needs Attention
-
Changes in Hot Water
It is not necessarily the case that the cylinder problem will be characterised by a visible leak. If the hot water temperature is reduced, there are fluctuations in heating times, or there is reduced hot water, then there could be some malfunction in the system.
-
Unusual Noises or Pressure Changes
Banging noises, humming, or any other odd noises could mean deposits, heating problems, or problems with components. Pressure changes could also put more stress on connections. Pressure issues with hot water cylinders should be considered along with other symptoms.
-
Damp Areas and Water Staining
It is necessary to inspect the presence of any indication of constant wetness, marks around the pipes, or dampness beneath the cylinder. The smallest drop can ultimately have an impact on the nearby floors, walls, or other fittings.
Conclusion
A leak in your hot water tank should not be taken lightly but viewed as a practical matter needing appropriate attention. Identifying the source early enough will enable you to keep your house safe, have efficient heating of water, and make necessary decisions about repairing or replacing it. When looking for ‘repair hot water cylinder near me’ seek professional help at Squires and Duran Plumbing & Heating on hot water tanks.
FAQs
Can one fix the problem of a leaking hot water cylinder?
It depends on the situation, but it is possible to fix the problem of a leaking cylinder through the repair of its valve, seal, connector, and pipe.
How will I know if the cylinder is leaking?
In case any leakages of water occur from the cylinder, then the issue arises with the cylinder itself and not the connections.
Is a small cylinder leak a serious issue?
A small leak causes damages gradually and the problem will increase if the leak is not detected after some days. It is important that the problem be known right away in order not to suffer any more damages.
Why do I have my cylinder leaking at the valve?
My cylinder is leaking at the valve because of wear and tear, bad seals, or bad connections. It is very important that one should know the actual reason for the leakage in order to fix it.
How long do hot water cylinders last?
The lifespan of different kinds of cylinders depends on many factors such as type, water used, installation, and maintenance. Old cylinders require checking when there are any changes in performance.
Read More...